How Does a Mortgage Work? A Simple Guide for Homebuyers
A plain-language walkthrough of how a mortgage actually works — principal, interest, escrow, amortization, and what happens over the life of the loan.
- A mortgage is a loan secured by your home — the lender can foreclose if you stop making payments, which is why the home itself backs the loan.
- Your monthly payment is generally made up of principal, interest, and — for most borrowers — property taxes and homeowners insurance held in an escrow account.
- Early in the loan, most of each payment goes toward interest; later, more goes toward principal. This shift is called amortization.
- Mortgage insurance may apply depending on your loan type and down payment — it protects the lender, not you, and works differently across loan programs.
This article is for general informational purposes and does not constitute financial, insurance, legal, or tax advice.
Table of Contents
- What a Mortgage Actually Is
- Principal: The Amount You’re Borrowing
- Interest: The Cost of Borrowing
- Loan Term: How Long You Have to Repay
- Down Payment: What You Pay Upfront
- Your Monthly Payment: What It’s Actually Made Of
- Property Taxes and Homeowners Insurance
- Mortgage Insurance, Where It Applies
- Escrow: How Taxes and Insurance Actually Get Paid
- Amortization: How Your Payment Splits Over Time
- Closing: Where the Loan Actually Starts
- What Happens Over the Life of the Loan
- Mortgage Basics Checklist
Buying a home usually means borrowing most of its price. That loan — the mortgage — is one of the biggest financial commitments most people ever make, but the mechanics behind it are more straightforward than they first appear. Here’s a plain-language walkthrough of what a mortgage actually is and how it works, from application to the day it’s paid off.
What a Mortgage Actually Is
A mortgage is a loan used to buy real estate, where the property itself secures the debt. In practice, that means if you stop making payments, the lender generally has the legal right to foreclose — take back the property and sell it to recover what’s owed. That security is exactly why mortgage interest rates are typically much lower than rates on unsecured debt like credit cards: the lender has collateral to fall back on.
The relationship has two sides. You, the borrower, agree to repay the loan according to its terms. The lender — a bank, credit union, or mortgage company — provides the funds and holds a lien on the property until the loan is paid off or refinanced.
Principal: The Amount You’re Borrowing
The principal is the amount of money you borrow to buy the home (or, over time, the remaining balance you still owe). If you buy a $350,000 house with a $70,000 down payment, your starting principal is $280,000. Every payment you make chips away — in part — at this number.
Interest: The Cost of Borrowing
Interest is what the lender charges you for the use of its money, expressed as a percentage of your loan (your interest rate). It’s separate from fees or closing costs. A lower interest rate means a lower cost to borrow the same amount, which is why comparing rates across lenders matters — even a fraction of a percentage point can add up substantially over a 15- or 30-year term.
Loan Term: How Long You Have to Repay
The loan term is the length of time you have to repay the loan in full — commonly 15, 20, or 30 years in the U.S. A shorter term generally means higher monthly payments but less interest paid in total over the life of the loan; a longer term generally spreads payments out and lowers them monthly, at the cost of more total interest. Neither is inherently “better” — it depends on your budget and goals.
Down Payment: What You Pay Upfront
Your down payment is the portion of the purchase price you pay upfront, in cash, rather than borrowing. Down payment requirements vary by loan program, lender, and borrower circumstances — some conventional and government-backed programs allow down payments well below 20%. A larger down payment generally reduces your loan amount and may affect your rate or whether mortgage insurance applies, but the right amount depends on your own finances and the specific loan you’re using.
Your Monthly Payment: What It’s Actually Made Of
For most borrowers, the monthly mortgage payment is made up of several distinct pieces, often abbreviated PITI:
- Principal — reduces your loan balance
- Interest — the cost of borrowing
- Taxes — your share of annual property taxes, collected monthly
- Insurance — your homeowners insurance premium, and mortgage insurance if it applies
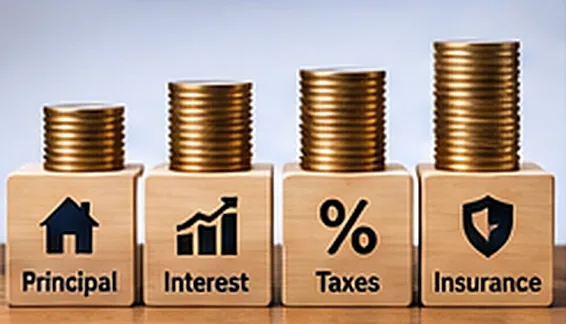
Hypothetical example: Say a borrower has a $280,000 loan at a fixed rate. Their monthly principal-and-interest payment might be a certain fixed dollar amount every month. On top of that, their lender adds an estimated monthly amount for property taxes and homeowners insurance. Their full monthly bill is the sum of both — not just the loan payment. (These are illustrative, made-up numbers, not a quote — your own figures depend entirely on your loan amount, rate, term, location, and insurance costs.)
Property Taxes and Homeowners Insurance
Property taxes are set by your local government and generally change over time as assessed values or tax rates change. Homeowners insurance protects the home (and satisfies a requirement most lenders impose). Both are recurring costs of owning the home — separate from the loan itself — but most lenders collect a share of each with your monthly mortgage payment rather than leaving you to pay large lump sums once or twice a year.
Mortgage Insurance, Where It Applies
Depending on your loan type and down payment, your payment may also include mortgage insurance, which protects the lender (not you) if you default. This isn’t universal — it depends on your specific loan program and down payment size, and conventional loans (private mortgage insurance) and FHA loans (FHA mortgage insurance premium) handle it differently. We cover this in detail in our guide to PMI.
Escrow: How Taxes and Insurance Actually Get Paid
Many lenders set up an escrow account to hold the portion of your payment earmarked for property taxes and insurance. Rather than you paying those bills directly, your servicer collects a monthly amount, holds it in the account, and pays the tax authority and insurance company when those bills come due. This spreads out large annual or semi-annual bills into predictable monthly amounts — though escrow accounts are periodically reviewed and adjusted if actual tax or insurance costs turn out higher or lower than estimated.
Amortization: How Your Payment Splits Over Time
Even though your principal-and-interest payment on a fixed-rate loan generally stays the same every month, how it’s divided between principal and interest changes throughout the loan. This process is called amortization.
Early in the loan, your balance is at its highest, so more of each payment covers interest, and comparatively little reduces the principal. As the balance drops, interest owed drops too, so a growing share of each payment goes toward principal — until, by the end of the term, nearly the whole payment is principal.
Closing: Where the Loan Actually Starts
Closing is the final step where ownership transfers and the loan officially begins. At closing, you sign the loan documents, pay any remaining closing costs and your down payment, and the lender disburses funds to complete the purchase. Our guide to mortgage closing costs breaks down what’s typically included.
What Happens Over the Life of the Loan
Putting it all together, a typical mortgage’s life cycle looks something like this:
- You apply and, often, get preapproved before house-hunting seriously.
- You find a home, agree on a price, and finalize your loan application.
- The lender provides a Loan Estimate outlining projected costs and terms.
- You close on the loan — signing documents and paying closing costs.
- You make monthly payments that amortize over your loan term, generally covering principal, interest, and (via escrow) taxes and insurance.
- If applicable, mortgage insurance may fall away once you reach sufficient equity.
- At the end of the term (or upon selling, refinancing, or paying it off early), the loan is satisfied and the lien on your home is released.
Mortgage Basics Checklist
- Understand the difference between your interest rate and your full monthly payment
- Confirm whether your loan will use an escrow account for taxes and insurance
- Ask your lender how your specific loan amortizes and whether mortgage insurance applies
- Compare loan terms (15-year vs. 30-year, for example) against your own budget and goals
- Read your Loan Estimate carefully before committing to a lender
Understanding these fundamentals makes every later step of the mortgage process — preapproval, comparing loan offers, closing — much easier to follow.
Frequently Asked Questions
What's the difference between my interest rate and my APR?
Your interest rate is the cost of borrowing the principal, expressed as a percentage. Your annual percentage rate (APR) is generally broader — it's meant to reflect the interest rate plus certain other loan costs, expressed as a yearly rate, which is why the APR on a Loan Estimate is often a bit higher than the interest rate itself.
Does my full monthly payment go toward paying off my loan?
Not necessarily. If you have an escrow account, part of your monthly payment covers property taxes and homeowners insurance (and mortgage insurance, if applicable) rather than your loan balance. Only the principal and interest portion reduces what you owe on the loan itself.
Why does more of my payment go to interest at the start?
Interest is generally calculated on your current loan balance, which is highest at the beginning of the loan. As you pay down principal over time, the balance drops, so less of each payment is needed for interest and more goes toward principal — the amortization process described above.
Is a bigger down payment always better?
A larger down payment generally reduces how much you borrow and may help you avoid mortgage insurance or qualify for a better rate, but it also means less cash on hand. Whether that tradeoff makes sense depends on your own finances, other savings goals, and the specific loan program — this is worth discussing with a lender or financial advisor rather than assuming one answer fits everyone.
What happens if I miss a mortgage payment?
Consequences vary by lender, loan type, and how far behind you fall, but missing payments can lead to late fees, damage to your credit, and — if it continues — foreclosure proceedings. If you're at risk of missing a payment, contacting your loan servicer as early as possible is generally recommended, since some programs offer hardship options.
Can my monthly payment change over time?
It depends on your loan type and what's included in your payment. A fixed-rate loan's principal-and-interest amount stays the same, but your total monthly payment can still change if your property taxes, homeowners insurance premium, or mortgage insurance cost changes, since those are often re-estimated periodically.