Replacement Cost vs. Actual Cash Value: What's the Difference?
How replacement cost and actual cash value settle homeowners insurance claims differently, with a comparison table and hypothetical examples.
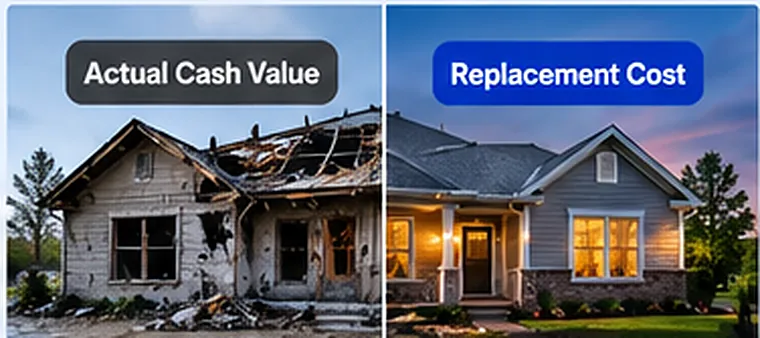
- Replacement cost value (RCV) generally pays to repair or replace covered property without subtracting for depreciation; actual cash value (ACV) subtracts depreciation from that cost.
- Many RCV policies pay in two steps: an initial ACV-based payment, then the remaining recoverable depreciation once repairs are completed and documented.
- Your dwelling and your personal property can be settled under different methods within the same policy.
- Your own declarations page — not a general article like this one — is the only reliable source for which settlement method applies to you.
This article is for general informational purposes and does not constitute financial, insurance, legal, or tax advice.
Table of Contents
- What Is Replacement Cost Value (RCV)?
- What Is Actual Cash Value (ACV)?
- How Depreciation Works
- Replacement Cost vs. Actual Cash Value: A Side-by-Side Comparison
- Hypothetical Example: The Same Loss Under RCV vs. ACV
- Dwelling vs. Personal Property: Do They Use the Same Method?
- How Replacement Cost Claim Payments Typically Work
- Policy Limits and What Happens If Rebuilding Costs More
- Why Policy Wording Matters
- Questions Homeowners Can Ask Their Insurer
- Which Should You Choose?
- Key Terms Recap
When your insurer settles a homeowners claim, the amount you receive often comes down to one key distinction: whether your policy pays replacement cost value or actual cash value. The difference can mean thousands of dollars, so it’s worth understanding before you ever need to file a claim.
What Is Replacement Cost Value (RCV)?
Replacement cost value is generally the amount it would take to repair or replace damaged property with materials of similar kind and quality, at current prices, without subtracting anything for the item’s age or wear. If a 10-year-old roof is damaged, an RCV settlement is typically based on what a comparable new roof costs today — not a discounted, “used” value.
What Is Actual Cash Value (ACV)?
Actual cash value is generally calculated as the replacement cost minus depreciation. Depreciation accounts for the age, wear, and remaining useful life of the damaged item. According to the NAIC, this is the core distinction between the two settlement types: ACV factors in how much value an item has already lost before the loss occurred.
How Depreciation Works
Depreciation is typically estimated using the item’s age, expected useful life, and condition. Insurers may use different depreciation schedules or software, so the exact percentage applied to any one item can vary between companies. What stays constant is the concept: the older and more worn an item is, the more its ACV settlement is generally reduced compared to its replacement cost.
Replacement Cost vs. Actual Cash Value: A Side-by-Side Comparison
| Replacement Cost Value (RCV) | Actual Cash Value (ACV) | |
|---|---|---|
| What it pays | Cost to repair/replace with similar new materials | Replacement cost minus depreciation |
| Accounts for age/wear? | No | Yes |
| Typical payout | Generally higher | Generally lower |
| Typical premium | Generally higher | Generally lower |
| Common payment structure | Often two payments (ACV amount, then recoverable depreciation after repairs) | Usually a single payment |
This is a general comparison, not a description of any specific insurer’s product — always confirm the details against your own policy.
Hypothetical Example: The Same Loss Under RCV vs. ACV
Suppose a covered fire damages a home’s kitchen, including a 10-year-old refrigerator with an estimated useful life of 15 years and a replacement cost of $1,500.
- Under ACV, the insurer might depreciate the refrigerator based on its age relative to its useful life, resulting in a lower payout — for illustration, perhaps in the neighborhood of $500-$600.
- Under RCV, the insurer would generally pay closer to the full $1,500 replacement cost, though possibly in two steps as described below.
These numbers are entirely hypothetical and only meant to illustrate the concept — actual depreciation calculations depend on your insurer’s methods and your policy’s terms.
Dwelling vs. Personal Property: Do They Use the Same Method?
Not necessarily. It’s common for a policy to apply replacement cost to the dwelling (the structure itself) while applying actual cash value to personal property (belongings), or to offer replacement cost on both for an additional premium. Some homeowners are surprised to learn their contents are settled differently than their home’s structure — checking both coverage sections on your declarations page avoids that surprise later.
How Replacement Cost Claim Payments Typically Work
If your policy includes replacement cost coverage with recoverable depreciation, claims are often paid in two parts:
- An initial payment based on the actual cash value of the damaged property.
- A second payment — the recoverable depreciation — once you complete the repair or replacement and provide documentation, such as a paid receipt or contractor invoice.
Not every policy includes recoverable depreciation, and the documentation requirements and any deadline to claim it can vary by insurer, so this is worth confirming directly with your company.
Policy Limits and What Happens If Rebuilding Costs More
Every policy has a coverage limit for the dwelling and for personal property. If the actual cost to rebuild exceeds your dwelling limit, you would generally be responsible for the difference — unless you’ve purchased extended or guaranteed replacement cost coverage, which some insurers offer to provide a cushion above the stated limit. Reviewing your dwelling limit periodically, especially after renovations or years of rising construction costs, is a reasonable practice.
Why Policy Wording Matters
The terms “replacement cost” and “actual cash value” can appear in different parts of a policy — for the dwelling, other structures, and personal property sections can each specify their own settlement method. Endorsements can also modify the default. Because of this, a general explanation like this one can describe the concepts, but only your own policy documents describe what applies to your specific coverage.
Questions Homeowners Can Ask Their Insurer
- Does my policy pay replacement cost or actual cash value for the dwelling? For personal property?
- If I have RCV, is depreciation recoverable, and what documentation do I need to collect it?
- Is there a time limit to submit that documentation after a covered loss?
- What happens if my rebuilding cost exceeds my dwelling coverage limit?
- Can I add extended or guaranteed replacement cost coverage, and what does it cost?
Which Should You Choose?
This depends on your own circumstances rather than a universal answer. Homeowners who want a higher likelihood of being able to fully rebuild or replace belongings without a large out-of-pocket gap often lean toward replacement cost coverage, accepting a higher premium in exchange. Homeowners more focused on minimizing premium costs, or with older belongings they don’t expect to fully replace at full price, may find actual cash value acceptable. If you’re unsure, your insurance agent can walk through both options using your actual policy numbers rather than hypothetical ones. Understanding your deductible alongside your settlement method also matters, since both affect what you’d actually receive after a loss.
Key Terms Recap
- Replacement cost value (RCV): Pays to repair/replace with similar new materials, no depreciation subtracted.
- Actual cash value (ACV): Replacement cost minus depreciation.
- Depreciation: The reduction in value due to age, wear, and remaining useful life.
- Recoverable depreciation: The withheld portion of an RCV payout, released after repairs are completed and documented.
- Coverage limit: The maximum your policy pays for a given category, regardless of settlement method.
Frequently Asked Questions
Is replacement cost coverage always better than actual cash value?
Not necessarily for every homeowner. RCV policies generally cost more in premium and typically result in a larger payout, while ACV policies cost less upfront but pay less at claim time. Which makes more sense depends on your budget, the age and value of your property, and how much risk you're comfortable carrying yourself.
What is recoverable depreciation, and how do I claim it?
If your policy is RCV and includes recoverable depreciation, your insurer typically withholds the depreciation amount from the first payment and reimburses it after you complete repairs or replacement and submit proof, such as receipts or a contractor's invoice. The exact process and any time limit to claim it varies by insurer, so ask directly.
Does replacement cost coverage mean I'll get a brand-new, upgraded home?
Generally no. Replacement cost typically covers rebuilding with materials of similar kind and quality to what was damaged, not an upgrade. If you want higher-end finishes or a larger home than what you had, you'd likely need to cover that difference yourself unless your policy says otherwise.
Can my dwelling and my personal property be settled differently?
Yes, this is common. Many policies let you choose (or default to) different settlement methods for the structure of your home versus your personal belongings — for example, replacement cost on the dwelling and actual cash value on contents. Check your declarations page for each coverage separately.
What happens if the cost to rebuild is more than my policy's dwelling limit?
Generally, your insurer pays up to your policy's stated limit, and you would be responsible for costs above that, unless you have specific extended or guaranteed replacement cost coverage, which some insurers offer as an add-on. This is a good question to ask your agent before you need it.
How do I find out which settlement method my policy actually uses?
Check your declarations page, or ask your agent or insurance company directly. The terminology to look for typically includes phrases like "replacement cost," "actual cash value," or references to specific coverage forms.
Does replacement cost coverage cost significantly more in premium?
It's generally priced higher than actual cash value coverage, since it typically results in larger claim payouts, but exactly how much more varies by insurer, location, and the property itself. Ask for a side-by-side quote if you're comparing the two.