Homeowners Insurance Deductible Explained: How It Works
How homeowners insurance deductibles work, including dollar and percentage deductibles, hurricane deductibles, and how to choose an amount.
- A deductible is generally the amount you pay out of pocket before your insurer pays the rest of a covered claim.
- Deductibles can be a flat dollar amount or, for certain perils like wind or named storms, a percentage of your dwelling coverage.
- As of mid-2025, 19 states plus Washington, D.C. have laws specifically addressing hurricane or named-storm deductibles, and the exact triggers vary by state and insurer.
- Choosing a deductible is a tradeoff between your premium and your out-of-pocket risk — there's no single right answer for every homeowner.
This article is for general informational purposes and does not constitute financial, insurance, legal, or tax advice.
Table of Contents
- What Is a Homeowners Insurance Deductible?
- How Deductibles Generally Work
- Dollar Deductibles
- Percentage Deductibles
- Special Wind and Hurricane Deductibles
- Hypothetical Claim Calculations
- How Your Deductible Relates to Your Premium
- Factors to Consider When Selecting a Deductible
- Policy-Specific Differences to Check
- Common Deductible Misunderstandings
- Homeowners Insurance Deductible Checklist
Your deductible is one of the most important numbers on your homeowners policy, yet many homeowners don’t think about it until they’re in the middle of filing a claim. Here’s how deductibles generally work, the different forms they can take, and what to weigh when choosing one.
What Is a Homeowners Insurance Deductible?
A deductible is generally the amount you’re responsible for paying before your insurance company pays the remaining covered amount on a claim. If a covered loss totals $8,000 and your deductible is $1,000, your insurer would typically pay $7,000, and you’d be responsible for the first $1,000.
How Deductibles Generally Work
Deductibles typically apply per claim, not per policy year, meaning each new covered loss is subject to the deductible again. Some homeowners assume a single annual deductible covers every claim in a given year — that’s not typically how it works, so it’s worth confirming with your insurer if you’re unsure.
Dollar Deductibles
The most common type is a flat dollar deductible — a fixed amount like $500, $1,000, or $2,500, regardless of the size of the claim. This is typically the default deductible that applies to most types of covered losses under a standard policy.
Percentage Deductibles
For certain perils, insurers may instead use a percentage deductible — a deductible calculated as a percentage of your dwelling coverage amount rather than a flat dollar figure. According to the NAIC, percentage deductibles for wind, hail, or hurricane coverage commonly range from around 1% to 15%, though the exact figure depends on your insurer, your state, and your property’s location.
Hypothetical example: If your dwelling coverage is $300,000 and your wind/hail deductible is 2%, that deductible would be $6,000 for a wind or hail claim — instead of whatever flat dollar deductible might apply to other types of losses.
Special Wind and Hurricane Deductibles
Coastal and hurricane-prone states often have separate rules for wind, hurricane, or “named storm” deductibles. As of mid-2025, the NAIC reports that 19 states plus Washington, D.C. have laws specifically addressing hurricane or named-storm deductibles. Importantly, the NAIC also notes that “no two laws are identical” — the specific trigger that activates a hurricane deductible (such as an official hurricane warning, or landfall within a certain distance of your property) varies by both state and insurer.
Hypothetical Claim Calculations
| Scenario | Dwelling Coverage | Deductible | Covered Loss | Insurer Pays (approx.) |
|---|---|---|---|---|
| Flat deductible | $250,000 | $1,000 | $6,000 | $5,000 |
| 2% wind/hail deductible | $250,000 | $5,000 (2%) | $6,000 | $1,000 |
| 5% hurricane deductible | $250,000 | $12,500 (5%) | $6,000 | $0 (loss is below deductible) |
These figures are simplified, hypothetical illustrations to show how the math works — not a projection of what any real claim would pay.
How Your Deductible Relates to Your Premium
In general, deductibles and premiums move in opposite directions: choosing a higher deductible typically lowers your premium, because you’re agreeing to absorb more of the cost yourself before coverage kicks in. Choosing a lower deductible typically raises your premium, since the insurer is taking on more of the risk. The exact tradeoff — how much premium you save for a given deductible increase — varies by insurer and location, so it’s worth requesting a real quote comparison rather than assuming a universal ratio.
Factors to Consider When Selecting a Deductible
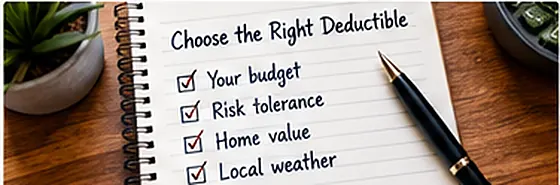
- Your emergency savings. Could you comfortably cover your deductible in cash if you needed to file a claim tomorrow?
- Your area’s risk exposure. Homeowners in wind- or hurricane-prone regions may weigh percentage deductibles more heavily than someone inland.
- How often you expect to file claims. A homeowner who rarely expects to file a claim may lean toward a higher deductible for the ongoing premium savings.
- Whether you have separate savings earmarked for home repairs.
- Your overall budget for the premium itself.
This is general information, not individualized financial advice — a licensed agent can help you weigh these factors against your actual policy quote.
Policy-Specific Differences to Check
- Does your policy have one deductible, or separate deductibles for wind/hail, hurricane, or other specific perils?
- If you have a percentage deductible, is it based on your dwelling coverage amount, and how is that amount currently set?
- Does your state require insurers to offer a choice between a percentage and flat-dollar hurricane deductible?
- Has your deductible changed at your last renewal?
Common Deductible Misunderstandings
- Assuming one deductible covers the whole year. Most deductibles apply per claim, not annually.
- Not realizing a percentage deductible can be much larger than a flat one. A 2% deductible on a $400,000 home is $8,000 — often more than homeowners expect.
- Filing a claim for damage below the deductible. This typically results in no payout and can still appear in your claims history.
- Forgetting that a hurricane deductible may apply even if the storm wasn’t officially a “hurricane” at landfall, depending on how your state and policy define the trigger.
Homeowners Insurance Deductible Checklist
- Confirm your standard deductible on your declarations page
- Check whether a separate wind/hail or hurricane deductible applies
- If it’s a percentage deductible, calculate the actual dollar amount based on your current dwelling coverage
- Compare premium quotes at a couple of different deductible levels
- Make sure you understand what your policy actually covers before deciding how much deductible risk to take on
- Revisit your deductible choice if your savings or risk tolerance changes
Frequently Asked Questions
Do I pay my deductible every time I file a claim?
Generally, yes — most homeowners policies apply the deductible per claim, not per year. Some policies use different deductibles for different types of losses (like a separate hurricane deductible), so you could have more than one deductible amount depending on the cause of loss.
Can I change my deductible after I've bought a policy?
In most cases, yes — you can typically ask your insurer or agent to adjust your deductible at renewal or sometimes mid-term, which will usually change your premium accordingly. Confirm the effective date of any change and how it affects a claim already in progress.
What happens if the damage costs less than my deductible?
If the covered repair cost is at or below your deductible, your insurer generally wouldn't pay anything, since you're responsible for that amount first. Many homeowners choose not to file a claim at all in this situation, since a claim on record can factor into future underwriting even with no payout.
Do all types of claims use the same deductible?
Not necessarily. It's common for a policy to have one standard deductible for most claims, plus a separate, often percentage-based deductible that applies specifically to wind, hail, hurricane, or named-storm damage, depending on your state and insurer.
Is choosing a higher deductible always the better financial choice?
Not universally — it depends on your savings, your risk tolerance, and how likely you think you are to file a claim. A higher deductible generally lowers your premium, but it also means more out-of-pocket cost if you do have a covered loss. This is a personal finance tradeoff, not a one-size-fits-all answer.
What is a hurricane or named-storm deductible, and how is it different?
It's a separate deductible — often a percentage of your dwelling coverage rather than a flat dollar amount — that applies specifically when a hurricane or named storm causes the damage. According to the NAIC, the specific trigger that activates this deductible (such as a formal hurricane warning or landfall within a certain distance) varies by state law and by insurer.
Where do I find my exact deductible amount or amounts?
Check your policy's declarations page, which should list your standard deductible and any separate deductibles (like wind/hail or hurricane) that apply. If anything is unclear, your agent or insurance company can confirm the exact figures and how they're triggered.